MiFID / MiFIR
The Markets in Financial Instruments Directive (MiFID) is a cornerstone of EU financial services legislation and is of direct relevance to asset management companies. In 2014, the European Commission adopted new rules revising MiFID, consisting of a Directive (MiFID II) and a regulation (MiFIR). Overall, MiFID II yielded positive results in terms of liquidity and transparency for investors.
Among possible improvements to the MiFID framework, EFAMA encourages the creation of a well-structured, reasonably priced consolidated tape managed by ESMA and fed by all trading venues and systematic internalisers for all financial instruments. A second, long-term EFAMA objective is better enforcement of data providers’ existing obligation to provide market data on a “reasonable commercial basis”.
Joint letter on open Access and Interoperability in Cash Equities Clearing
EFAMA response to ESMA’s call for evidence on the Structure of European Equity Markets
Latest Parliament report takes the Market Integration and Supervision Package in the wrong direction
Turning ESMA into an extra supervisor for asset managers is unwarranted, a major distraction, and runs contrary to the EU competitiveness and simplification agendas
Joint letter on open Access and Interoperability in Cash Equities Clearing
EFAMA response to ESMA’s call for evidence on the Structure of European Equity Markets
Latest Parliament report takes the Market Integration and Supervision Package in the wrong direction
Turning ESMA into an extra supervisor for asset managers is unwarranted, a major distraction, and runs contrary to the EU competitiveness and simplification agendas
Buy-side use-cases for a real-time consolidated tape
A real-time consolidated tape, provided it is made available at a reasonable cost, will bring many benefits to European capital markets. A complete and consistent view of market-wide prices and trading volumes is necessary for any market, though this is especially true for the EU where trading is fragmented across a large number of trading venues. A real-time consolidated tape should cover equities and bonds, delivering data in ‘as close to real-time as technically possible’ after receipt of the data from the different trade venues.
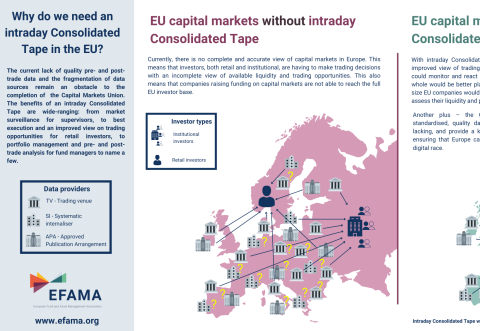
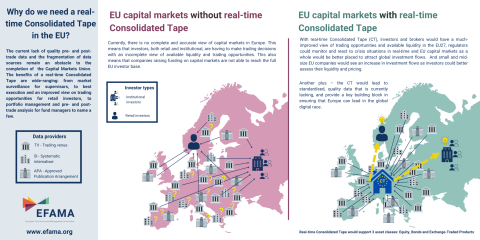
Visual | Why do we need a real-time Consolidated Tape in the EU?
The current lack of quality pre- and post-trade data and the fragmentation of data sources remain an obstacle to the completion of the Capital Markets Union. The benefits of a real-time Consolidated Tape are wide-ranging: from market surveillance for supervisors, to best execution and an improved view on trading opportunities for retail investors, to portfolio management and pre- and post-trade analysis for fund managers to name a few.
Investment Funds Distributor Due Diligence Questionnaire
Funds face unique challenges in performing intermediary oversight, and especially so because of MiFID II requirements, changing regulatory landscapes, and the absence of an industry agreed-upon standard between funds and their distribution channels. To help address these challenges, a dedicated working group developed a uniform due diligence questionnaire (DDQ) that will serve as the standard for investment funds (UCITS and AIFs) in performing onboarding and ongoing oversight of distribution channels.
Navigating the MiFIR Review: (Part 2) Consolidated Tape & Market Data