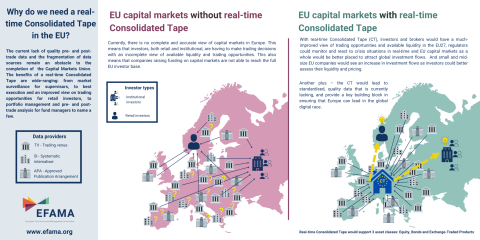
In a letter to policymakers, 18 European buy-side firms state that only an Equities/ETFs tape that delivers data in real-time and that includes pre-trade data in the form of 5 layers of best bid and offer, will meet with the necessary market demand to make the Equities/ETFs Consolidated Tape commercially viable. A reasonably priced tape is also a precondition for success, they argue.
MiFID / MiFIR
The Markets in Financial Instruments Directive (MiFID) is a cornerstone of EU financial services legislation and is of direct relevance to asset management companies. In 2014, the European Commission adopted new rules revising MiFID, consisting of a Directive (MiFID II) and a regulation (MiFIR). Overall, MiFID II yielded positive results in terms of liquidity and transparency for investors.
Among possible improvements to the MiFID framework, EFAMA encourages the creation of a well-structured, reasonably priced consolidated tape managed by ESMA and fed by all trading venues and systematic internalisers for all financial instruments. A second, long-term EFAMA objective is better enforcement of data providers’ existing obligation to provide market data on a “reasonable commercial basis”.
Related policy positions
Policy Position
14 April 2023
European asset managers in full support of the European Parliament's proposal on Equities Consolidated Tape
Policy Position
17 January 2023
MiFIDII/ MiFIR review - EFAMA-BVI-EFSA-NSA priorities
The MiFID/MiFIR review will be key to the future success and competitiveness of the EU's capital markets.
With international competition for investment heating up markedly, European legislators need to ensure that EU regulation is helping, and not hindering, capital market growth and participation.
Various European trade associations representing EU capital markets, including EFAMA, BVI, EFSA and NSA, have published a letter outlining their main priorities for the review. This includes the following core elements:
Policy Position
11 July 2022
EFAMA responses to the discussion questions within the IOSCO report “corporate bond markets – drivers of liquidity during covid-19 induced market stresses”
EFAMA is appreciative of the opportunity to comment on this major IOSCO study on the dynamics of bond market liquidity during market stresses. We provide some detailed responses below, but would reiterate a few high-level points here:
Related news
Policy Position
Capital Markets
07 July 2026
Joint letter on open Access and Interoperability in Cash Equities Clearing
Policy Position
Capital Markets
MIFID
Capital Markets Union
01 July 2026
EFAMA response to ESMA’s call for evidence on the Structure of European Equity Markets
Press Release
Capital Markets
EMIR
MIFID
Capital Markets Union
EU Fund regulation
Supervision
18 June 2026
Latest Parliament report takes the Market Integration and Supervision Package in the wrong direction
Turning ESMA into an extra supervisor for asset managers is unwarranted, a major distraction, and runs contrary to the EU competitiveness and simplification agendas
Related publications
Publication
Capital Markets
MIFID
Data
Distribution & Client Disclosures
04 March 2020
3 Questions to Rudolf Siebel on Market Data Costs
Q #1 Have you witnessed an increase in the cost of market data over the last couple of years? If so, how can it be explained?
Past events
Members Only
EFAMA & AFME
Navigating the MiFIR Review: (Part 2) Consolidated Tape & Market Data
Virtual