MiFID / MiFIR
The Markets in Financial Instruments Directive (MiFID) is a cornerstone of EU financial services legislation and is of direct relevance to asset management companies. In 2014, the European Commission adopted new rules revising MiFID, consisting of a Directive (MiFID II) and a regulation (MiFIR). Overall, MiFID II yielded positive results in terms of liquidity and transparency for investors.
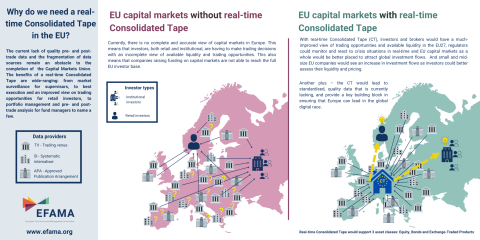
Among possible improvements to the MiFID framework, EFAMA encourages the creation of a well-structured, reasonably priced consolidated tape managed by ESMA and fed by all trading venues and systematic internalisers for all financial instruments. A second, long-term EFAMA objective is better enforcement of data providers’ existing obligation to provide market data on a “reasonable commercial basis”.
EFAMA response to ESMA's CP on MiFIR report on Systematic Internalisers in non-equity instruments
EFAMA Reply: ESMA CP on review report MiFIR transparency regime for equity, ETFs & other related instruments
Joint Statement on Market Data Costs
Reasonable Market Data Costs Benefits the Real Economy
The fundamental function of a trading venue is to match buyers and sellers of securities at a price that balances supply and demand through transparent rules and processes. The sale of market data is a related but separate by-product of that primary function.
Joint letter on open Access and Interoperability in Cash Equities Clearing
EFAMA response to ESMA’s call for evidence on the Structure of European Equity Markets
Latest Parliament report takes the Market Integration and Supervision Package in the wrong direction
Turning ESMA into an extra supervisor for asset managers is unwarranted, a major distraction, and runs contrary to the EU competitiveness and simplification agendas
3 Questions to Rudolf Siebel on Market Data Costs
Q #1 Have you witnessed an increase in the cost of market data over the last couple of years? If so, how can it be explained?
Navigating the MiFIR Review: (Part 2) Consolidated Tape & Market Data