EFAMA has some concerns with ESMA’s clarifications. In the consultation paper (CP), ESMA seems to have a very broad interpretation of the ‘multilateral systems’ definition under MiFID II and states that ‘systems where trading interests can interact but where the execution of transactions is formally undertaken outside the system still qualify as a multilateral system and should be required to seek authorisation’ (paragraph 36).
MiFID / MiFIR
The Markets in Financial Instruments Directive (MiFID) is a cornerstone of EU financial services legislation and is of direct relevance to asset management companies. In 2014, the European Commission adopted new rules revising MiFID, consisting of a Directive (MiFID II) and a regulation (MiFIR). Overall, MiFID II yielded positive results in terms of liquidity and transparency for investors.
Among possible improvements to the MiFID framework, EFAMA encourages the creation of a well-structured, reasonably priced consolidated tape managed by ESMA and fed by all trading venues and systematic internalisers for all financial instruments. A second, long-term EFAMA objective is better enforcement of data providers’ existing obligation to provide market data on a “reasonable commercial basis”.
Related policy positions
Policy position
25 November 2020
EFAMA's reply to ESMA's CP on MiFID II / MiFIR review on the functioning of Organised Trading Facilities (OTF)
Policy position
Capital Markets
Distribution & Client Disclosures
EU Fund regulation
UCITS
23 November 2020
EFAMA's reply to ESMA's CP on MiFIR Review report on the obligations to report transactions & reference data
We disagree with an extension of its scope to UCITS’ and AIFs’ management companies to the scope of the reporting requirements imposed by MiFIR, Art. 26. This extension would be in breach of the principle of proportionality, as:
Policy position
Capital Markets
14 September 2020
EFAMA comments EC CP on a Covid-19 Capital Markets Recovery Package
EFAMA appreciates the Commission's efforts in pursuing an alleviation of certain MiFID II requirements in the interest of promoting a swift recovery from the economic crisis precipitated by the Covid-19 pandemic (....).
EFAMA believes however that there are more effective ways to foster SME access to markets and urges the Commission to consider a set of further measures (...)
Related news
Infographic
Capital Markets
MIFID
Capital Markets Union
Data
06 October 2021
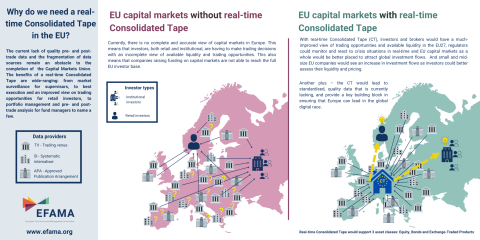
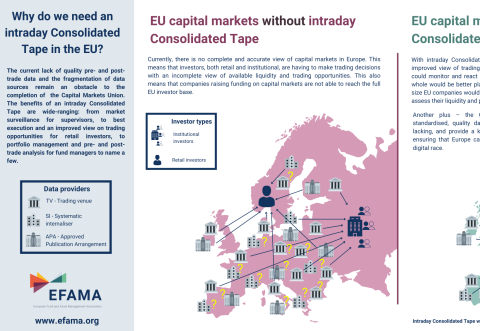
Visual | Why do we need a real-time Consolidated Tape in the EU?
The current lack of quality pre- and post-trade data and the fragmentation of data sources remain an obstacle to the completion of the Capital Markets Union. The benefits of a real-time Consolidated Tape are wide-ranging: from market surveillance for supervisors, to best execution and an improved view on trading opportunities for retail investors, to portfolio management and pre- and post-trade analysis for fund managers to name a few.
Policy Position
Capital Markets
MIFID
07 July 2021
Ensuring a market structure and a transparency regime which facilitate liquidity, investors’ choice, and funding of companies | Joint statement
Well-functioning and liquid capital markets are fostered by an efficient market structure and supporting legislative frameworks. A diverse and efficient market structure reduces the costs of trading whilst promoting best execution. This optimises funding opportunities for issuers and maximises returns for investors and savers.
Announcement
MIFID
Competitiveness
Distribution & Client Disclosures
15 February 2021
FinDatEx launches interim version of European MiFID Template
The Financial Data Exchange Templates (FinDatEx) platform today published an interim version of the European MiFID Template (EMT V3.1) which is available on the FinDatEx website. The purpose of this interim version is to answer the demand of product distributors and manufacturers to cope with the basic implementation of MiFID II ESG/SFDR principles, and in view of the misaligned application dates of SFDR Level 1, SFDR RTS and MiFID II delegated acts.
Related publications
Publication
Capital Markets
MIFID
Data
Distribution & Client Disclosures
04 March 2020
3 Questions to Rudolf Siebel on Market Data Costs
Q #1 Have you witnessed an increase in the cost of market data over the last couple of years? If so, how can it be explained?